


 Login


Annual Income
Read Time: 8 Mins


PRODUCTS
 Payroll Suite
 HR Suite
 Talent Suite
 Project Services Suite
Meet the platform tailored to your business
Core system of record
One platform for the entire employee journey
How Srijan Technologies streamlined timesheets management with Keka
Read customer story
Anarock replaces fragmented HR processes with one platform for 2,500+ employees
Read the story
BY INDUSTRY
BY COMPANY SIZE
LEARN
EXPLORE KEKA
Navigate every labor law, wage regulation, and statutory requirement across all 28 states and 8 union territories without the legal headaches.
Learn More
Annual income is the total amount of money an individual earns during a financial year. In India, this 12-month period runs from April 1 to March 31 of the following year. It includes earnings such as salary, wages, commissions, bonuses, overtime pay, and tips. Depending on the context, annual income may refer to gross income before deductions or net income after applicable deductions.
Annual income includes the money an individual earns from employment, investments, property, business activities, and other sources during a financial year. For salaried employees in India, this may include basic salary, dearness allowance (DA), house rent allowance (HRA), leave travel allowance (LTA), bonuses, and commissions. The tax treatment of these components depends on the applicable income tax rules and the individual’s circumstances.
Under Section 14 of the Income-tax Act, 1961, income was classified under five heads for income tax purposes:
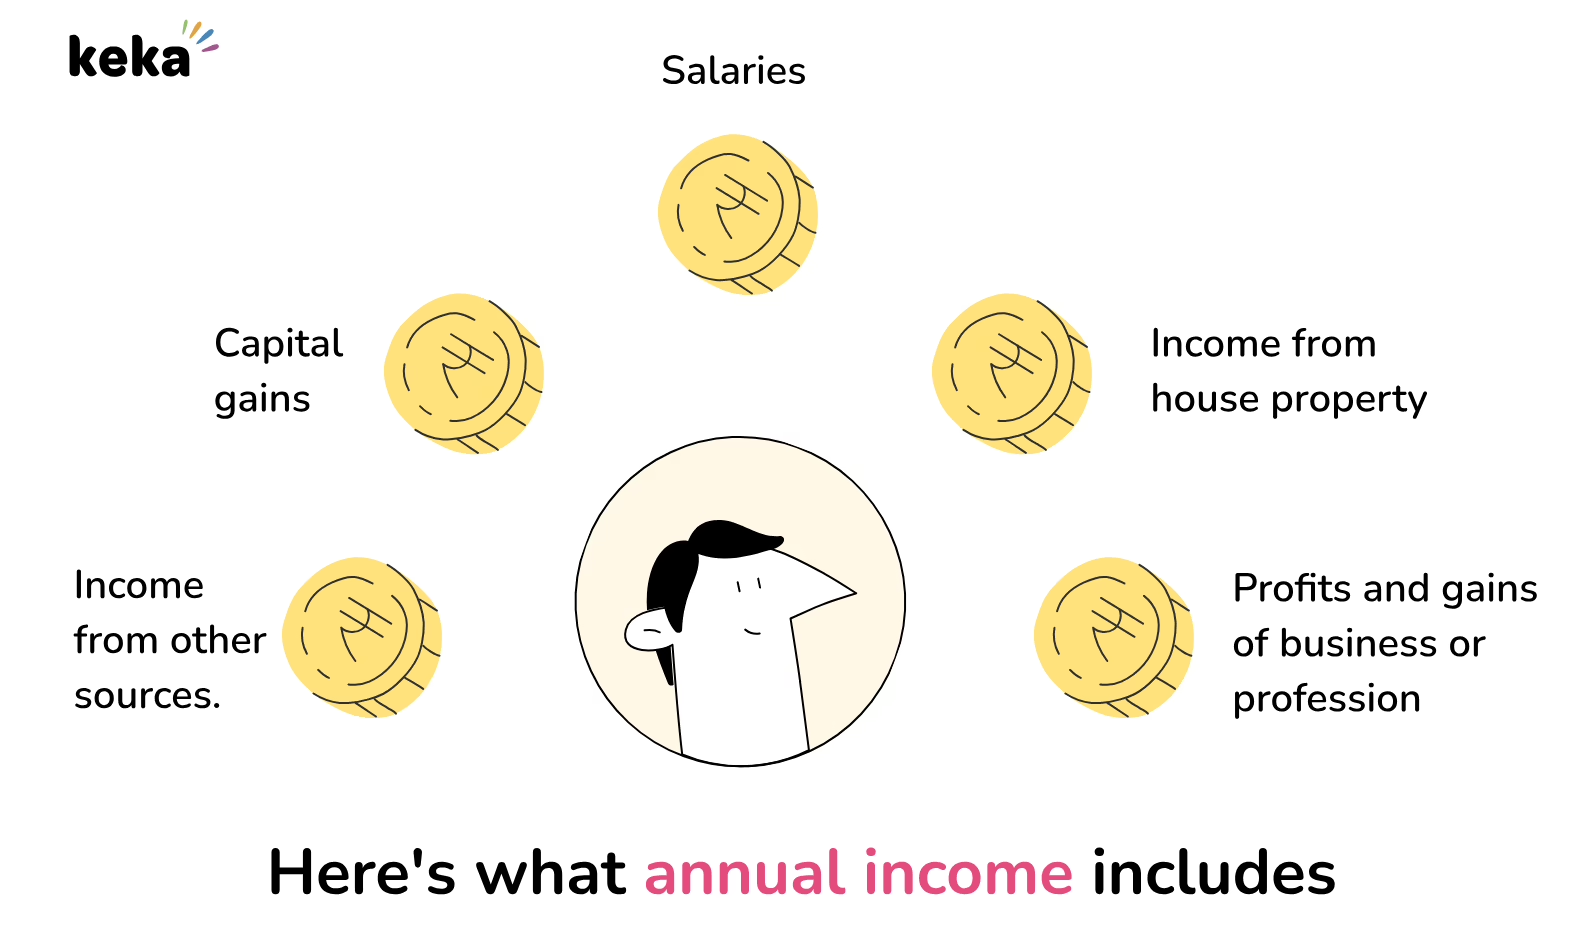
Salaries: Income received from employment, including salary and applicable allowances.
Income from house property: Income earned from owning and renting out property, subject to applicable tax rules.
Profits and gains of business or profession: Income earned through business activities or professional services.
Capital gains: Profits arising from the transfer of capital assets, such as property or shares.
Income from other sources: Income that falls under this category, such as interest income and certain dividend income.
These categories help determine an individual’s income for tax purposes. However, annual income and taxable income are not necessarily the same because certain deductions, exemptions, and other tax provisions may apply.
Some components of a salary package require separate consideration. Employer contributions to a provident fund may be subject to tax rules and applicable limits. Gratuity may receive tax exemptions when the relevant conditions are met, and reimbursements may be taxable or exempt depending on their nature and the applicable rules. Therefore, these items should not automatically be excluded from annual income calculations.
To verify annual income in India, individuals can refer to salary slips, bank statements, income tax returns, and Form 16 (now Form 130), which employers provide to employees as a certificate containing salary-related income, applicable deductions or exemptions, and tax deducted at source (TDS). Other sources of income may require additional supporting documents, such as interest certificates, investment statements, or rental records.
Annual income refers to the total income an individual earns over 12 months. Employees typically receive their salaries in monthly or other scheduled payments throughout the year.
For a salaried employee receiving a fixed monthly salary, annual salary can generally be estimated by multiplying the monthly salary by 12.
For example:
If an employee earns ₹50,000 per month, their estimated annual salary would be:
₹50,000 × 12 = ₹6,00,000 per annum (₹6 lakh per year).
This is a basic estimate that assumes the monthly salary remains constant for 12 months. Actual annual earnings may vary depending on factors such as bonuses, commissions, salary revisions, and the period worked during the financial year.
Gross annual income generally refers to the total income an individual earns over a year before applicable deductions. Net annual income refers to the amount remaining after accounting for relevant deductions and taxes. The exact calculation depends on whether the income being considered is employment income, income from other sources, or business income.
Gross Annual Income
Definition: Gross annual income is the total income an individual earns during a year before applicable deductions. For salaried employees, it generally includes salary and other taxable components of employment income.
Components: Depending on the individual’s circumstances, gross annual income may include salary, bonuses, commissions, rental income, interest, and dividends.
Calculation: Gross annual income can generally be estimated by adding the relevant income earned from different sources during the year. The calculation may differ depending on the type of income being considered.
Significance:
Tax planning: Gross income is one of the factors used to determine taxable income and the applicable income tax liability.
Loan applications: Lenders may ask applicants to provide their gross annual income when assessing loan eligibility and repayment capacity. Requirements vary by lender and loan product.
Financial planning: Understanding gross annual income helps individuals assess their earnings and plan their finances.
Net Annual Income
Definition: Net annual income generally refers to the amount remaining after applicable deductions and taxes are accounted for. For salaried employees, the amount received after payroll deductions is commonly referred to as take-home pay.
Components: For salaried employees in India, payroll deductions may include tax deducted at source (TDS), employee contributions to the Employees’ Provident Fund (EPF), and Professional Tax (PT), where applicable. The amounts deducted depend on the employee’s circumstances, salary structure, and applicable rules.
Calculation: Net income can be estimated by subtracting applicable deductions and taxes from gross income. For salaried employees, the calculation should account for the deductions applicable to their payroll.
Significance:
Budgeting: Net income helps individuals estimate the amount available for regular expenses, savings, and investments.
Financial decisions: Understanding net income helps individuals assess their spending capacity and plan for financial commitments.
Annual income is the total income an individual earns from relevant sources during a financial year. To estimate it, add the income earned from employment, investments, property, business activities, and other applicable sources during that period.
For salaried employees in India, the calculation may involve adding salary components such as basic salary, dearness allowance (DA), house rent allowance (HRA), special allowances, and bonuses. The components included depend on the employee’s salary structure and the income being calculated.
Steps to calculate annual income
Step 1: Identify your sources of income.
List the income earned during the financial year, including salary, bonuses, commissions, interest, dividends, rental income, and other applicable sources.
Step 2: Add your salary components.
For a salaried employee, gross salary can be estimated by adding the applicable salary components before deductions.
For example, consider the following illustrative monthly salary structure:
| Salary component | Monthly amount |
|---|---|
| Basic salary | ₹40,000 |
| Dearness allowance (DA) | ₹5,000 |
| House rent allowance (HRA) | ₹10,000 |
| Special allowances | ₹8,000 |
| Total monthly salary before bonus | ₹63,000 |
If the employee also receives an annual bonus of ₹60,000, the estimated annual salary would be:
₹63,000 × 12 + ₹60,000 = ₹8,16,000 per annum (₹8.16 lakh).
This is an illustrative calculation, assuming the monthly salary components remain unchanged throughout the year and the employee receives the stated bonus. Actual annual earnings may vary depending on the salary structure, bonuses, revisions, and the period worked.
Step 3: Include income from other sources.
If the individual also earns interest, dividends, rental income, or other income, add the relevant amounts to calculate total annual income. Ensure that income is counted only once and that the calculation covers the same financial year.
Step 4: Verify the figures.
Salary slips, bank statements, investment statements, and income tax records can help verify income. For salary details, refer to the applicable tax deduction certificate. Form No. 130, Part C (Annexure-I) contains the detailed salary computation, including the breakup of gross salary, exemptions, and deductions.
You can also use an income calculator or financial software to estimate annual income. Check the inputs and assumptions before relying on the result.
Monthly salary to annual salary conversion
The following table illustrates how a fixed monthly salary translates into an annual amount when the same salary is received for 12 months.
| Monthly salary | Illustrative annual salary |
|---|---|
| ₹25,000 | ₹3,00,000 (₹3 lakh) |
| ₹30,000 | ₹3,60,000 (₹3.6 lakh) |
| ₹40,000 | ₹4,80,000 (₹4.8 lakh) |
| ₹50,000 | ₹6,00,000 (₹6 lakh) |
| ₹60,000 | ₹7,20,000 (₹7.2 lakh) |
| ₹75,000 | ₹9,00,000 (₹9 lakh) |
| ₹1,00,000 | ₹12,00,000 (₹12 lakh) |
These figures are simple estimates based on a constant monthly salary for 12 months. They do not automatically account for bonuses, commissions, salary revisions, unpaid periods, or income from other sources.
Divide your annual salary by 12 to calculate the average monthly salary.
For example, if your annual salary is ₹6,00,000:
Monthly Salary = ₹6,00,000 ÷ 12
Monthly Salary = ₹50,000
This calculation gives an average monthly amount before deductions and assumes the salary is distributed evenly across 12 months.
In India, eligible resident individuals under the new tax regime pay no tax on total income up to ₹12 lakh because of the Section 87A rebate, subject to the applicable conditions. Beyond that, taxability depends on the applicable tax regime, the relevant tax year, the type of income, and eligible rebates and deductions.
For FY 2025–26, the new tax regime provides a rebate under Section 87A of the Income-tax Act, 1961 for eligible resident individuals with total income up to ₹12 lakh, subject to the applicable conditions. Special-rate income, such as certain capital gains, may be treated differently.
From April 1, 2026, the Income-tax Act, 2025 applies to Tax Year 2026–27 onwards. Check the applicable rules before calculating your tax liability.
An annual income calculation should include salary, bonuses, commissions, business income, rental income, interest, dividends, and other relevant earnings for the financial year. The exact calculation depends on whether you need gross annual income, taxable income, or net income after deductions.
Annual income refers to the money earned during a year, while Cost to Company (CTC) represents the employer’s total annual cost of employing an individual. CTC may include employer contributions, benefits, and other employment costs that do not form part of the employee’s take-home salary.
For this reason, annual CTC, gross annual salary, and net annual salary are not necessarily the same.
Subscribe to keep up with the latest strategic finance content.
Request a demo


