Login


Why This Employee’s ₹3.36 Lakh Tax Notice Should Force HR Teams to Rethink Compliance


PRODUCTS
 Payroll Suite
 HR Suite
 Talent Suite
 Project Services Suite

Meet the platform tailored to your business
Core system of record
One platform for the entire employee journey

BY INDUSTRY
BY COMPANY SIZE
LEARN
EXPLORE KEKA
A TDS default is often treated as a minor compliance lapse. In reality, it can have far wider consequences. Failure to deposit TDS can attract prosecution under Section 276B and leave employees dealing with tax demands that should never have been theirs. This article explains the legal implications of a TDS default and why businesses need stronger processes to verify that deductions are actually deposited.
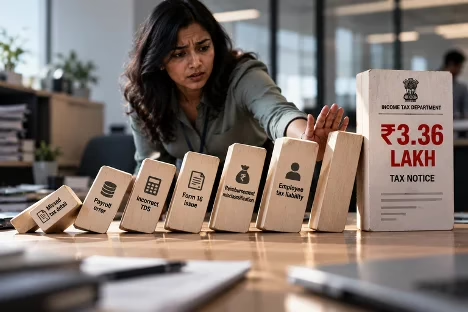
Sophia, a Mumbai-based IT employee, opened her income tax portal expecting a routine confirmation. Instead, she found a tax-demand for ₹3.36 lakh.
She hadn’t underpaid anything. Her employer, an IT services firm, had deducted ₹3.91 lakh in TDS from her salary that year as required. The deduction showed up on every payslip and in her Form 16. But only ₹79,030 of it actually reached the Income Tax Department.
It took her seven years of litigation before the Mumbai Income Tax Appellate Tribunal to get relief. The tribunal ultimately ruled that an employer’s failure to deposit TDS cannot become the employee’s tax burden.
While Sophia’s case eventually ended in her favour, it raises an uncomfortable question for any HR leader, founder, or finance head running payroll in an Indian SMB. If your company defaulted on a TDS deposit tomorrow, would your internal processes catch it before an employee did?
TDS works on a simple premise. The person or company paying you, called the deductor under the law, deducts tax and deposits it with the government on your behalf. The employee, called the deductee, gets credit for that tax once it shows up in their Form 26AS.
The law sets out a clear timeline for the deductor to follow, deduct TDS in the relevant month, deposit it by the 7th of the following month in most cases (March being the exception for non-government deductors), file quarterly TDS returns, and issue Form 16 (now Form 130) by 15 June of the next year for salary TDS.
Failure can become very expensive very soon. Interest applies under Section 201, a penalty equal to the unpaid amount applies under Section 271C, and criminal prosecution can follow under Section 276B if the deducted tax is never deposited.
Sophia’s case fits a pattern that shows up across Indian SMBs every assessment year. While deductions happen, the deposit doesn’t always reach the government. This gap usually surfaces months, and sometimes years, later in the form of a tax notice instead of an internal check.
For HR leaders, finance heads, and founders, the real question is whether your company would catch that gap on its own, or find out the way Sophia’s employer did, after the fact, with interest accruing and a tribunal case underway.
Defaults like this usually come from how payroll is structured internally rather than one deliberate decision.
The company that deducted the tax remains legally answerable for it. This is regardless of whether the failure traces back to an accountant, an overloaded finance executive, a software error, or simple oversight.
In most SMBs, one person handles deductions, challan uploads, and return filing. There is no second check. Reconciliation against Form 26AS, where it happens at all, tends to happen at year-end rather than monthly. Let us illustrate with a scenario.
Picture a payroll executive who processes April salaries, uploads the challan, and moves on to the next task. If that deposit doesn’t go through, there’s usually nothing in place to catch it until the mismatch shows up in Form 26AS at year-end, by which point interest has already been compounding for months.
Sophia’s case shows where the gap actually sits. The deduction itself isn’t in question. Her Form 16 and salary slips proved it, and that’s the documentary evidence she used before the tribunal. What never got confirmed by anyone is whether that deducted amount reached the government.
It’s a bit like a courier marking a package as picked up but never confirming it was actually delivered.
If your TDS vendor or finance team missed a deposit this quarter, would your reconciliation process catch it before it compounds into the kind of multi-year dispute and legal exposure this case represents?
The common assumption, reasonable on its face, is that a TDS default is a financial slip-up. Companies often approach this with the mindset that interest and penalties are manageable. All they have to do is write a cheque, and the matter closes with Finance taking the hit.
However, the law treats the stakes very differently.
Section 276B of the Income-tax Act makes failure to deposit deducted tax a criminal offence, punishable with rigorous imprisonment ranging from three months to seven years, alongside a fine, for the person or director responsible.
In an August 2013 press release, the CBDT stated that tax deductors who retain TDS beyond the due date and fail to deposit it with the government are liable for prosecution under Section 276B, irrespective of the period of retention.
To quote CBDT’s 2013 press release:
“Such retention of government dues beyond the due date is an offence liable for prosecution under Section 276B of the Income Tax Act, 1961.” — Ministry of Finance, Press Information Bureau, August 2013
This provision is regularly enforced. In 2018, the Tis Hazari Court ordered the judicial custody of a company director in Delhi after his company deducted TDS across three financial years and never deposited it, and he failed to offer a reasonable explanation for the delay. As Tax2Win co-founder Abhishek Soni has noted,
“…the deductor may face prosecution and imprisonment for up to seven years if they wilfully fail to deduct or deposit the TDS… This legal action has serious consequences and may have long-lasting implications for the deductor.” Abhishek Soni, Co-founder, Tax2Win
Courts have also held that the offence is largely technical in nature. The belated deposit itself is treated as evidence of the default, regardless of intent, which removes much of the “we didn’t mean to” cover that smaller companies tend to assume they have.
The employee carries a parallel exposure too. She cannot be taxed twice for the same income, but she still has to fight to prove that’s what happened.
| Section | Consequence | Who Can Be Held Liable |
|---|---|---|
| 201 | Interest on the unpaid amount | The deducting company |
| 271C | Penalty equal to the unpaid amount | The deducting company or the responsible person |
| 276B | Criminal prosecution, imprisonment of 3 months to 7 years | The responsible person or director |
A TDS default carries a criminal exposure that can sit on a director’s name. The only thing standing between a deduction and that outcome is whether anyone can prove, on demand, that the deposit actually happened.
There’s also a cost to employee trust once a default surfaces. An employee who finds out their TDS wasn’t deposited starts wondering about other things too, provident fund contributions, gratuity calculations, final settlement figures. That doubt tends to spread quickly across every other number on the payslip, and it eventually shows up in Glassdoor reviews, attrition, and a harder time hiring.
None of this means the answer is hiring three more people into payroll. For most SMBs, the more realistic fix is software built to track deduction, deposit, and filing as one chain, instead of stopping at deduction.
Platforms like Keka, for instance, can help with:
Automated calculations: Statutory deductions for PF, ESIC, TDS, and PT computed against current rules, reducing manual errors.
Filing-ready reports: Form 24Q, Form 26Q, ECR files, and challans generated as part of the workflow, so the quarterly return isn’t assembled from scratch each time.
Maker-checker approvals: Audit trails ensure a single payroll executive isn’t the only check before a deduction goes out.
Regulatory updates: Built-in tracking keeps the configuration aligned when rules change.
Employee self-service: Access to payslips, Form 16 (now Form 130), and tax summaries reduces the back-and-forth that lands on HR’s desk.
However, software can only take you so far. It can automate calculations, generate challans, and reduce manual errors. It cannot tell you whether someone actually checked that the deposit happened. That’s where process and ownership matter.
Tax authorities are not standing still on this.
Automated systems increasingly flag mismatches between what employers report as deducted and what actually lands in the government’s account, which means the gap between default and detection is shrinking every filing cycle. The SMBs likely to get caught in the next two or three years probably don’t have bad intentions. They simply never built a habit of checking their own work.
HR doesn’t deposit the tax, but it ends up answering for the gap when the numbers don’t match. The companies that hold up under scrutiny will be the ones that can prove, within minutes, that this month’s TDS was both deducted and deposited.
Subscribe to keep up with the latest strategic finance content.
Request a demo