Login


Balance Sheet vs Income Statement: Key Differences and Examples


PRODUCTS
 Payroll Suite
 HR Suite
 Talent Suite
 Project Services Suite

Meet the platform tailored to your business
Core system of record
One platform for the entire employee journey

BY INDUSTRY
BY COMPANY SIZE
LEARN
EXPLORE KEKA
Understanding both the balance sheet and income statement is essential to assess a company’s financial health. A balance sheet shows what a business owns and owes at a specific point in time. The income statement shows how a business earns and spends money over time. Together, they help HR, finance, and business leaders make informed decisions on hiring, budgeting, and growth.
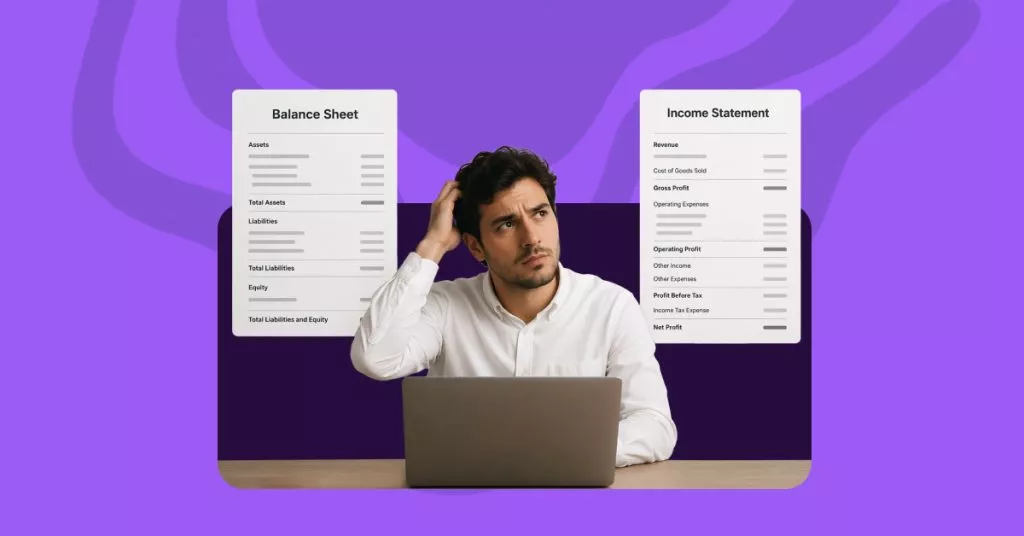
Sarah had been in HR for over a decade. She could negotiate benefits, plan headcount, and handle tough conversations with ease. But in a leadership meeting, when the CFO pulled up two financial statements and asked, “What does this mean for our hiring capacity?” she paused.
She’s not alone. Most HR professionals aren’t trained to read financial statements, yet these two documents, the balance sheet and the income statement, sit behind almost every workforce decision. Hiring plans, compensation changes, restructuring. It all traces back to these numbers.
At a basic level, the difference between balance sheet and income statement is simple. The balance sheet provides a snapshot of the organization’s financial standing at a specific moment. An income statement shows how much it earned or lost over a period.
In this blog, we’ll break down how each statement works, where they differ, and more importantly, what they actually signal for your business. For HR, this is not about learning finance. It is about making workforce decisions with financial clarity.
Key Takeaways: Balance Sheet vs Income Statement
- A balance sheet shows what a company owns and owes at a given point in time.
- An income statement shows how much a company earns or loses across a time period.
- One reflects financial position, the other shows financial performance.
- Both are essential for understanding business health and making informed decisions.
- For HR, these statements directly influence hiring, compensation, and workforce planning.
Let’s start with the balance sheet.
A balance sheet is a financial statement that captures a company’s financial position at a single, specific point in time. It shows what the business owns, what it owes, and what remains for the owners after debts are accounted for.
It does not show performance over time. It does not tell you whether last quarter was good or bad. It answers one precise question: What does this company look like financially, right now, on this date?
A balance sheet is organized into three core sections:
These three pieces work together to show the company’s financial position.
Every balance sheet is governed by one foundational accounting equation:
Assets = Liabilities + Equity
This equation must always balance. If it doesn’t, there’s a recording error somewhere in the books.
A balance sheet helps leaders answer:
For HR professionals, this matters most when evaluating whether the organization can support headcount growth, major benefit commitments, or long-term workforce investments. A strong balance sheet signals capacity to grow. A strained one signals caution.

The balance sheet answers the “what do we have” question. But it doesn’t tell you whether the business is actually earning money. For that, you need the income statement.
An income statement is a financial statement that shows how much money a business earned and spent over a defined period: a month, a quarter, or a full fiscal year. Where the balance sheet freezes a single moment, the income statement tracks what happened across time.
It is also commonly called a profit and loss statement, or simply a P&L. Its central question is: Is this business actually making money?
The income statement flows from top to bottom, with each line building on the last:
The basic formula for income statement is:
Net income = Revenue – Expenses
If revenue exceeds expenses, the company is profitable. If expenses outpace revenue, the company is operating at a loss.
An income statement helps leaders answer:
For HR professionals, the income statement is particularly relevant because employee compensation (salaries, bonuses, benefits, payroll taxes, and recruitment costs) runs directly through operating expenses. When labor costs rise, this statement reflects it immediately. That makes it essential reading during workforce planning cycles, compensation reviews, and annual budgeting.

Now that you understand what each statement does on its own, it’s worth putting them side by side, because the difference becomes much clearer when you see them compared directly.
At their core, these two statements answer different financial questions, serve different purposes, and inform different kinds of decisions.
Here is how they compare directly:
| Comparison Point | Balance Sheet | Income Statement |
| Purpose | Shows financial position | Shows financial performance |
| Timeframe | A single point in time | A period of time |
| Main Components | Assets, liabilities, equity | Profitability, cost control, efficiency |
| Financial Insight | Liquidity, solvency, net worth | Profitability, cost control, efficiency |
| Accounting Equation | Assets = Liabilities + Equity | Revenue – Expenses = Net Income |
| Best Used For | Assessing stability and financial health | Measuring performance and profitability |
It is worth noting that neither statement tells the full story alone. Investors, executives, and lenders use both together. A company can be profitable and financially fragile at the same time; you would only know that by reading both documents side by side.
Which brings up the question that gets asked most often: if you had to choose one, which statement matters more?
The honest answer is that it depends on who is asking and what decision they are trying to make. Both statements are essential, but they carry different weight for different stakeholders.
Investors typically need the full picture. The income statement shows whether the business is generating earnings. The balance sheet reveals whether those earnings are built on a stable financial foundation.
A company can look profitable on paper but carry dangerous levels of debt. Investors don’t just want profits, they want profits supported by financial strength. Most experienced investors treat both statements as equally necessary before committing capital.
Most business owners watch the income statement closely. Is the business making money? Are margins holding? Are costs under control? Profitability is the daily pulse check.
But the balance sheet matters too, especially when owners need to understand debt levels, available equity, or whether cash flow can carry the next phase of growth. A business can be profitable on paper and still struggle to make payroll if assets are tied up or liabilities are stacking up.
Lenders lean heavily on the balance sheet. Before extending credit, they need to know whether the business has enough assets and financial stability to repay a loan, and that answer lives on the balance sheet.
They also review the income statement to confirm the business generates enough consistent income to meet monthly repayment obligations. In practice, lenders want evidence of both current stability and reliable cash generation.
So the real question isn’t which statement is more important. It’s knowing when to use each one, and that depends on the situation.
Both statements are necessary, but they are most useful in different situations. Knowing which one to reach for, and when, leads to sharper, faster decisions.
A balance sheet is the right tool when you need to understand the company’s current financial position: not how it performed last quarter, but where it stands today.

For HR teams, a balance sheet becomes especially relevant during organizational restructuring, expansion planning, or leadership discussions about sustained workforce investment. If the company is considering a major hiring push or a significant benefits overhaul, the balance sheet frames whether the financial base can actually support it.
An income statement is the right tool when you need to measure results and track how performance has changed across time.

For HR professionals, this statement is most useful during workforce planning seasons. If headcount is up, overtime is climbing, or benefits costs are rising, the income statement is where those changes show up and where leadership will come looking for context.
So what does this mean for HR in practice?
HR may not own either of these financial statements, but its decisions directly shape both.
Employee compensation is typically one of the largest expenses in any business. Salaries, bonuses, benefits, recruitment, training, and payroll taxes all flow through the income statement as operating costs.
That means every significant workforce decision: a new hire, a pay increase, an expanded benefits program, has a direct, measurable effect on company profitability.
At the same time, long-term HR commitments can shape the balance sheet. Retirement obligations, severance liabilities, and deferred compensation arrangements all appear as liabilities. In growing organizations, workforce investment plans feed into broader financial discussions at the executive and board level.
When HR understands both statements, the function becomes meaningfully more effective:
In short, financial fluency gives HR the language to lead, and not just to participate.
A balance sheet tells you where a company stands. An income statement tells you how it got there. Used together, they give leaders, investors, and partners a complete picture of financial health that neither document can provide alone.
For HR professionals, the value of understanding both goes beyond finance fundamentals. It means asking better questions, having more credible conversations, and making workforce decisions that are genuinely aligned with where the business is headed.
The next time a CFO pulls up those two documents and asks what they mean for headcount, you’ll know exactly what to say.
A balance sheet shows a company’s financial position as of a specific date, including assets, liabilities, and equity. An income statement shows financial performance during a given timeframe, detailing revenue, expenses, and profit or loss. Together, they provide a complete view of business health.
The three main financial statements are the balance sheet, income statement, and cash flow statement. The balance sheet shows financial position, the income statement shows profitability, and the cash flow statement tracks how cash moves in and out of the business over time.
A balance sheet is also called a statement of financial position. In some contexts, it may be referred to as a statement of net worth. All these terms describe the same document that outlines a company’s assets, liabilities, and equity at a given point in time.
The income statement shows profitability. It outlines revenue, expenses, and net income over a specific period, helping businesses understand whether they are making a profit or operating at a loss. It is the primary statement used to evaluate financial performance.
Subscribe to keep up with the latest strategic finance content.
Request a demo