Login


Section 80C Deduction: Complete Tax Savings Guide Under Income Tax Act 2025


PRODUCTS
 Payroll Suite
 HR Suite
 Talent Suite
 Project Services Suite

Meet the platform tailored to your business
Core system of record
One platform for the entire employee journey

BY INDUSTRY
BY COMPANY SIZE
LEARN
EXPLORE KEKA
Section 80C remains one of the most effective ways to reduce taxable income under the old tax regime. This guide explains the complete 80C deduction list for FY 2025-26, eligible investments, deduction limits, tax calculations, old vs new regime differences, and filing requirements. Learn how to maximise tax savings, avoid common mistakes, and simplify payroll compliance with smarter investment planning.
Section 80C is one of the most widely used income tax deductions under the Income Tax Act, 1961. It allows individuals and Hindu Undivided Families (HUFs) to reduce their taxable income by up to ₹1.5 lakh each financial year through eligible investments and expenses such as PPF, EPF, ELSS, life insurance premiums, home loan principal repayment, and tuition fees. The deduction is available only under the old tax regime.
In this guide, you’ll find the complete Section 80C deduction list for FY 2025-26, understand who can claim the deduction, how the ₹1.5 lakh limit works, which investments offer the best tax-saving opportunities, how Section 80C compares with related deductions, and the practical steps HR teams and employees can take to maximise tax savings while staying compliant.
Section 80C reduces your total taxable income before tax is calculated on it.It’s a reduction applied earlier in the process, and the ceiling for that reduction is a maximum deduction of ₹1.5 lakh in a financial year.
The deduction applies to a mix of investments and specific expenses:
Life insurance premiums
NSC and similar fixed-income instruments
Tuition fees
Home loan principal repayment
However, none of this helps if you’ve opted for the new tax regime, since Section 80C simply doesn’t exist there.
Numbers make this easier to explain than definitions do. Take an employee with a salary income of ₹10,00,000 and other income of ₹1,00,000.
| Particulars | With 80C Claimed | Without 80C Claimed |
|---|---|---|
| Salary income | ₹10,00,000 | ₹10,00,000 |
| Less standard deduction | (₹50,000) | (₹50,000) |
| Other income | ₹1,00,000 | ₹1,00,000 |
| Gross total income | ₹10,50,000 | ₹10,50,000 |
| Less Section 80C deduction | (₹1,50,000) | |
| Taxable income | ₹9,00,000 | ₹10,50,000 |
| Total tax payable (incl. cess) | ₹96,200 | ₹1,32,600 |
Takeaway:
That’s a saving of ₹36,400 from one deduction alone. It’s the kind of number that makes the case for early tax planning better than any explanation of the mechanics could.
Once the basic mechanism is clear, the next question employees usually ask is where the ceiling sits and how it interacts with related sections. That’s worth unpacking before moving to eligibility.
The maximum deduction under Section 80C is ₹1,50,000 per financial year, and that ceiling covers the combined amount across every eligible instrument, not each one separately.
This trips people up more than any other rule in the section: an employee who splits money across PPF, ELSS, and life insurance premiums doesn’t get three separate ₹1.5 lakh allowances. They draw from one shared pool.
| Section | Eligible investments | Maximum deductions | Part of combined limit under 80CCE |
|---|---|---|---|
| 80C | ELSS, PPF or EPF, life insurance premium, home loan principal, SSY, NSC, SCSS | ₹1,50,000 | Yes |
| 80CCC | Contributions to pension funds | ₹1,50,000 | Yes |
| 80CCD(1) | Employee’s contributions to NPS | ₹1,50,000 | Yes |
| 80CCD(1B) | Contributions to notified pension schemes such as Atal Pension Yojana | ₹50,000, subject to conditions | No, this is an additional deduction |
Example: An employee invests ₹60,000 in PPF, ₹50,000 in ELSS, and ₹60,000 in life insurance premiums, a total of ₹1.7 lakh. The deduction still caps at ₹1.5 lakh. The extra ₹20,000 doesn’t disappear from the investment, it just stops counting toward tax savings.
There’s a separate ₹50,000 available under Section 80CCD(1B) for NPS contributions, sitting outside this combined limit, which is why total tax-saving potential under these sections can stretch to ₹2 lakh.
Section 80CCE is the rule tying Sections 80C, 80CCC, and 80CCD(1) together under one shared ceiling of ₹1.5 lakh. It’s more useful to think of these as one bucket rather than three, since that’s how the tax calculation actually treats them.
Important tip:
Present 80C, 80CCC, and 80CCD(1) as a single ₹1.5 lakh pool during investment declaration season. Employees plan better when they see the shared cap up front, rather than discovering it after they’ve overcommitted to one instrument.
With the limit clear, eligibility is the next natural stop, since not everyone filing a return can actually claim this deduction.
Individuals and HUFs can claim Section 80C deductions. Companies, firms, and LLPs cannot.
| Taxpayer type | Can claim 80C? | Notes |
|---|---|---|
| Resident individual | Yes | Under old tax regime only |
| Hindu Undivided Family (HUF) | Yes | Up to ₹1.5 lakh |
| NRI (Non-Resident Indian) | Yes | If filing under the old regime, some investments are restricted |
| Company/Firm/LLP | No | Not eligible |
Payroll and finance teams run into this most often when employee declarations include family investments made through joint accounts or HUF structures. Matching the investment to the right taxpayer type before it’s logged makes the rest of the review far smoother.
Yes. An HUF can claim up to ₹1.5 lakh under Section 80C, provided:
The investment is made from HUF funds, not a member’s personal account.
The instrument itself qualifies, e.g. life insurance premiums for HUF members, PPF contributions, or ELSS investments made through the HUF account.
Yes, with conditions. NRIs can claim Section 80C on eligible instruments provided they’re filing under the old tax regime, but eligibility needs a check instrument by instrument:
Generally accessible: Life insurance, ELSS, children’s tuition fees
Often restricted: PPF, spending on the account and residency rules
Eligibility settled, the natural next step is the full list of what actually qualifies.
Employees rarely need the legal language. What they want is one list they can check against their own investments.
The full 80C deduction list for FY 2025-26:
Life insurance premium payments
Equity Linked Savings Scheme (ELSS) mutual funds
National Savings Certificate (NSC)
Sukanya Samriddhi Yojana (SSY)
5-year tax-saving fixed deposits
Senior Citizen Savings Scheme (SCSS)
Home loan principal repayment
Stamp duty and registration charges on property purchase
Tuition fees paid for up to two children
Every item on this list draws from the same ₹1.5 lakh pool. If an employee has already used part of the limit through EPF or PPF contributions, whatever’s left is what remains available for the rest.
Different employees want different things from a tax-saving investment: safety, growth, or the shortest possible lock-in. Comparing the options side by side usually settles the decision faster than describing each one individually.
| Investment Option | Average Interest/Return | Lock-in Period | Risk Factor |
|---|---|---|---|
| ELSS Funds | 12% – 15% | 3 years | High |
| NPS Schemes | 8% – 10% (market linked) | Till 60 years of age | Depends on fund choice |
| ULIP | 8% – 10% | 5 years | Medium |
| Tax Saving FD | Up to 8.40% | 5 years | Low |
| PPF | 7.90% | 15 years | Low |
| Senior Citizen Savings Scheme | 8.60% | 5 years, extendable by 3 years | Low |
| National Savings Certificate | 7.90% | 5 years | Low |
| Sukanya Samriddhi Yojana | 8.50% | Till girl child reaches 21 years | Low |
A rough way to position these for employees: ELSS for growth, PPF and NSC for stability, tax-saving FDs for predictability.
Not every 80C claim is an investment. A few genuine expenses qualify too:
Life insurance premiums
Children’s tuition fees, full-time education only
Home loan principal repayment
Stamp duty and registration charges on a residential property purchase
Watch out:
Stamp duty is claimed in the year the payment is made, not the year the property is registered or occupied. Timing matters if someone’s mid-purchase around the financial year end.
With the full list covered, it’s worth breaking down each major instrument individually, starting with the one most people already know.
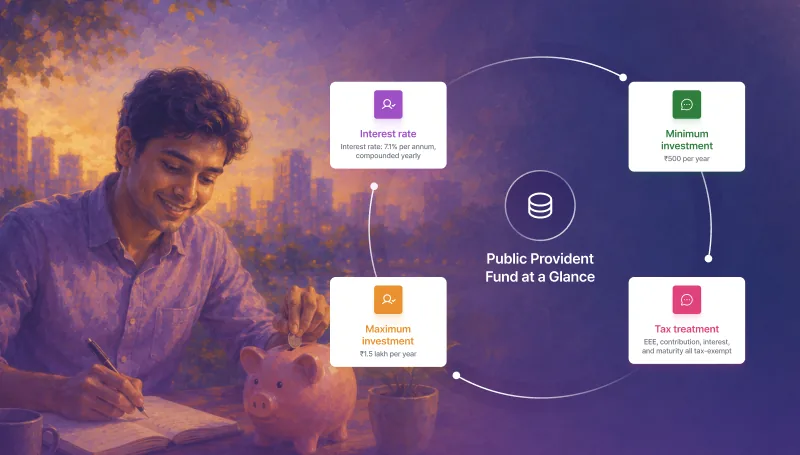
PPF combines stability, tax savings, and forced long-term discipline in one product, which is why it remains the default recommendation for risk-averse savers.
Account tenure and lock-in: 15 years
Post maturity: Extend in 5-year blocks, with or without further contributions
Partial withdrawal: Allowed after 5 years, capped at 50% of the balance calculated against a prescribed reference year
Loan facility: Available after 1 year, up to a set percentage of the account value
Contributions qualify under Section 80C, though the deduction still sits inside the overall ₹1.5 lakh old-regime cap. Next up is EPF, the one deduction almost every payslip touches, and the one most commonly misread.
For most salaried employees, EPF is the first Section 80C deduction they start claiming, often without realising it. Since contributions are deducted automatically every month, many employees have already used a significant portion of the ₹1.5 lakh limit before they invest a single rupee in PPF, ELSS, or life insurance.
Only the employee’s contribution to EPF qualifies for deduction under Section 80C. This is generally 12% of basic salary plus dearness allowance for eligible employees.
The employer’s matching contribution doesn’t qualify under Section 80C. It’s governed by separate tax provisions and shouldn’t be included while calculating the employee’s 80C deduction.
Common mistake:
Employees often assume the full EPF line item on their payslip, including the employer’s share, counts toward their 80C limit. Only their own contribution does. This distinction matters most when employees cross-check Form 16 against their tax-saving declarations.
Before finalising your tax-saving investments, check how much of the limit has already been utilised through EPF. It gives a much clearer picture of how much room is still available for investments such as PPF, ELSS, NSC, or life insurance premiums.
ELSS is the only mutual fund category eligible for an 80C deduction, which is why it’s usually the go-to option for anyone chasing equity-linked growth alongside tax savings.
| Investment | Returns | Lock-In Period | Tax on Returns |
|---|---|---|---|
| 5-Year Bank Fixed Deposit | 6.5% to 7.5% | 5 years | Yes |
| Public Provident Fund | 7.1% | 15 years | No |
|
National Savings Certificate |
7% to 8% | 5 years | Yes |
| National Pension Scheme | 8% to 10% | Till retirement | Partially taxable |
| ELSS Funds | 12% to 16% | 3 years | Partially taxable |
Younger employees, or anyone who wants a growth option without locking money away for a decade or more, tend to gravitate here.
Returns aren’t guaranteed since the fund tracks equity performance, so the upside can be strong in good years and flat or negative in weak ones.
Tax Note:
Gains above ₹1.25 lakh in a financial year are taxed at 12.5%. The 80C deduction on the original investment stays intact regardless.
ELSS is a long-term growth play rather than a substitute for fixed income. Life insurance follows a very different logic, and that’s the next stop.
Premiums paid to any IRDAI-approved insurer, public or private, qualify under Section 80C, and ULIPs fall under the same umbrella.
HUF-owned policies: The HUF can claim the deduction if the premium is paid from the HUF’s account, not an individual member’s.
Related but separate: Section 80CCC covers annuity plans from LIC or another insurer, and draws from the same ₹1.5 lakh combined ceiling rather than sitting outside it.
This is usually the easiest 80C claim to verify, since premium receipts are standard documentation most employees already keep. NSC works differently, and that difference is worth spelling out next.
NSC suits an employee who wants a government-backed, fixed-tenure instrument without market exposure. It currently offers 7.7% interest, compounded yearly and paid out at maturity, with a 5-year lock-in.
NSC interest is taxable, unlike PPF or SSY. The investment itself still qualifies for the 80C deduction, but the annual interest accrual doesn’t carry the same tax-free status.
Treat NSC as a tax-saving entry point with taxable growth, not a fully tax-free product. It works well for conservative investors who are comfortable holding for the full five years.
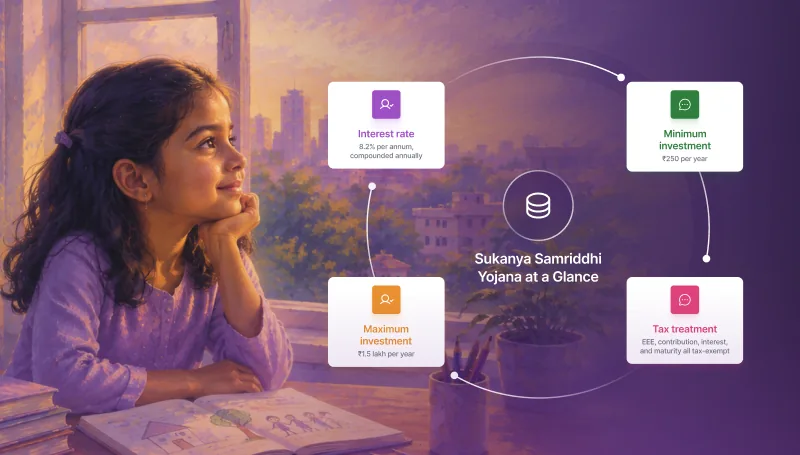
SSY is built for families planning long-term savings for a girl child, and it comes with one of the cleanest tax outcomes in the entire 80C list.
Account opened by a resident parent or guardian for a girl child under 10
Maximum two SSY accounts per family
Deposit period: 15 years from opening; maturity: 21 years from opening
NRIs cannot open a fresh account; if the girl child later becomes an NRI, the account must be closed permanently.
Partial withdrawal opens up once the girl child turns 18 or clears Class 10, whichever comes first.
Withdrawal capped at 50% of the balance at the end of the previous financial year.
Funds must go toward education or marriage expenses, and that purpose typically needs documentation.
SCSS pairs capital safety with regular payouts, which is what makes it a strong fit for retirees.
Interest rate: 8.2% per annum, paid quarterly
Tenure: 5 years, extendable by 3
Deduction: Up to ₹1.5 lakh under the old regime
Individuals aged 60 and above.
Retired civilian employees aged 55 to 60, and retired defence personnel aged 50 to 60, can invest within a month of receiving retirement benefits.
Minimum investment: ₹1,000; maximum: ₹30 lakh, in multiples of ₹1,000
NRIs and HUFs are not eligible.
The SCSS rate is 8.2% per annum, and interest is paid quarterly, which makes it attractive for retirees who need predictable cash flow. The investment qualifies for Section 80C deduction up to ₹1.5 lakh, but the interest earned is taxable in the hands of the investor.
A 5-year tax-saving FD qualifies for the deduction up to ₹1.5 lakh, and it’s usually the easiest instrument to explain since most employees already understand how an FD works.
Lock-in: 5 years mandatory and no premature withdrawal
Returns: Typically 6.5% to 7.5%
Interest: Fully taxable, unlike PPF
Compare that to ELSS, where a 3-year lock-in and equity exposure can deliver stronger post-tax returns for someone willing to take on market risk. Tax-saving FD works best as the conservative, easy-to-explain option for employees who’d rather not think about market movement at all.
Principal repayment on a home loan, along with stamp duty and registration charges on the purchase, both qualify under Section 80C.
Stamp duty and registration charges are deductible in the year the payment is actually made. Employees tend to remember the loan principal and forget the transaction costs, so it’s worth flagging separately.
Watch out:
There’s a five-year holding requirement. Sell the property within five years of the end of the purchase year, and the deduction claimed earlier can be reversed and taxed in the year of sale.
Home loan principal is best explained alongside home loan interest under Section 24(b), since the two work under separate provisions even though employees often lump them together as “the home loan tax benefit.”
Tuition fees paid for full-time education at a recognised institution in India qualify, capped at two children per taxpayer.
Excluded from the claim:
Development fees
Donations
Hostel charges
Transport costs
Exam fees
If it’s tuition, for full-time education, within the two-child limit, it belongs in the 80C basket. Everything else on that same invoice generally doesn’t.
A few eligible options get overlooked simply because they’re less commonly discussed than PPF or ELSS.
The India Post version of a tax-saving FD, with rates typically ranging from 6.9% to 7.5% depending on tenure. It works on the same principle as a bank tax-saving FD and belongs in the same conversation, even though employees rarely think to ask about it.
For general 80C claims: Eligible amount plus policy or document identification number.
For NPS-linked claims under 80CCD: Contribution amount plus the taxpayer’s PRAN.
Tip for payroll teams:
Asking for the right documentation fields upfront, rather than after the fact, cuts down on follow-up requests during the review cycle significantly.
Three sections, one shared ceiling. Section 80C covers the broadest set of investments and expenses, 80CCC covers annuity plans from insurers, and 80CCD covers NPS contributions.
| Section | Contribution Type | Deduction Limit | Old Regime | New Regime |
|---|---|---|---|---|
| 80CCD(1) | Taxpayer’s own NPS | Up to ₹1.5 lakh, within the 80C/80CCC combined | Yes | No |
| 80CCD(1B) | Taxpayer’s own additional NPS contribution | Up to ₹50,000 | Yes | No |
| 80CCD(2) | Employer’s NPS contribution | 10% or 14% of salary (Basic + DA) | Yes | No |
Worth flagging:
Unlike everything else in this table, the employer’s NPS contribution under 80CCD(2) stays deductible even under the new tax regime, making it one of the few benefits that survives the switch.
Section 80CCC applies to annuity plans of LIC or another insurer that are linked to a pension scheme. The deduction shares the same ₹1.5 lakh combined limit under Section 80CCE, so it does not sit outside the main 80C pool.
In practical terms, this section is narrower than 80C and is relevant mainly when an employee is contributing to insurer-backed pension products. It is useful to call this out because many taxpayers assume every retirement-linked product falls under the same cap in the same way.
An employee’s own NPS contribution is capped within the same combined ₹1.5 lakh ceiling, generally limited to 10% of basic pay plus dearness allowance for salaried employees.
This is the benefit most taxpayers leave on the table. It adds ₹50,000 on top of the ₹1.5 lakh combined limit, pushing the employee’s own total deduction potential to ₹2 lakh, but only under the old regime.
Section 80CCE caps 80C, 80CCC, and 80CCD(1) together at ₹1.5 lakh. Once that structure is clear, the regime question becomes the next stop, since it decides whether any of this applies at all.
This is the decision point that actually matters: Section 80C works only under the old tax regime.
| Deduction/Exemption | Old Regime | New Regime |
|---|---|---|
| Section 80C (PPF, NSC, Life Insurance, ELSS) | Available up to ₹1.5 lakh | Not available |
| HRA | Available, based on actuals | Not available |
| Standard Deduction (salaried) | ₹50,000 | ₹75,000 |
| Section 80D (health insurance) | Available | Not available |
| Interest on Housing Loan (Section 24) | Deduction up to ₹2 lakh | Not available |
The two standard deduction figures above aren’t a typo or a year-over-year change. They’re regime-specific: ₹50,000 under the old regime, ₹75,000 under the new one, both current for FY 2025-26.
No. Choosing the new regime rules out the 80C deduction entirely, even for employees who’ve already made qualifying investments in PPF, ELSS, or life insurance.
Take Mr. Rakesh, salary income of ₹25 lakh for FY 2025-26:
New regime tax liability: ₹3,19,800
Old regime tax liability, without deductions: ₹5,69,400
Gap in favor of the new regime: ₹2,49,600
That gap closes, and can reverse, once meaningful deductions enter the picture. An employee with a full 80C claim, HRA, home loan interest, and health insurance premiums may still come out ahead under the old regime despite its steeper slab rates. Run the comparison rather than assume either regime wins by default.
The calculation itself is straightforward. Once you’ve identified all eligible investments and expenses under Section 80C, the deduction is simply reduced from your Gross Total Income before your final tax liability is worked out. The only thing to remember is that the deduction cannot exceed ₹1.5 lakh in a financial year.
Take an employee earning a salary of ₹10,00,000 with an additional ₹1,00,000 from other sources. If they’ve invested ₹1,50,000 in PPF, here’s how the calculation works:
Salary income: ₹10,00,000
Less standard deduction: ₹50,000
Other income: ₹1,00,000
Gross total income: ₹10,50,000
Less Section 80C deduction: ₹1,50,000
Taxable income: ₹9,00,000
Total tax payable, including cess: ₹96,200
The deduction reduces the employee’s taxable income by ₹1.5 lakh, bringing it down from ₹10.5 lakh to ₹9 lakh. That translates into an estimated tax saving of ₹36,400 under the old tax regime.
The exact tax payable will still depend on the applicable slab, cess, and any other deductions claimed. But the principle stays the same. The lower your taxable income, the lower your tax liability.
Making an eligible investment is only half the job. To actually receive the tax benefit, the deduction needs to be reported correctly during payroll processing or while filing your Income Tax Return. Missing either step can lead to higher TDS during the year or a delayed refund later.
Here’s what the process typically looks like:
Complete eligible investments before 31st March of the relevant financial year.
Keep investment proofs and supporting documents ready.
Submit your investment declaration to your employer so payroll can calculate TDS accurately and reflect eligible deductions in Form 16.
While filing your ITR, report the eligible deduction under Chapter VI-A and verify that it matches your Form 16 and supporting documents.
Keep these documents handy before filing your return:
80C claims: Eligible amount, plus policy or document identification number.
NPS claims under 80CCD(1) and 80CCD (1B): Contribution amount, plus PRAN
Form 12BB: The declaration document used to support these claims through payroll,
Form 16: Consolidates income, deductions, exemptions, and TDS for the year.
The deduction remains the same regardless of the return you file. The only difference is the ITR form applicable to your income profile.
ITR-1: Resident individuals with total income up to ₹50 lakh from salary or pension, one house property, and other specified sources.
ITR-2: Individuals and HUFs who don’t fit ITR-1, with income from sources beyond business or profession.
ITR-3: Individuals and HUFs with income from business or profession.
The key is to ensure the deduction claimed in your return matches your investment records and supporting documents. A little time spent reconciling these details before filing can save unnecessary notices, refund delays, or correction requests later.
Bringing every instrument back into one table makes the trade-offs easier to see at a glance.
| Investment option | Average interest | Lock-in period | Risk factor |
|---|---|---|---|
| ELSS funds | 12% – 15% | 3 years | High |
| NPS scheme | 8% – 10% | Till 60 years of age | Depends on choice of funds |
| ULIP | 8% – 10% | 5 years | Medium |
| Tax saving FD | Up to 8.40% | 5 years | Low |
| PPF | 7.90% | 15 years | Low |
| Senior citizen savings scheme | 8.60% | 5 years, extendable by 3 years | Low |
| National Savings Certificate | 7.90% | 5 years | Low |
| Sukanya Samriddhi Yojana | 8.50% | Till girl child reaches 21 years | Low |
The pattern holds across most of these: ELSS offers the shortest lock-in and the strongest growth potential, PPF and SSY are built for long-term safety, SCSS suits retirees specifically, and tax saving FD or NSC works for predictability over market exposure.
None of it matters, though, if the employee has already opted into the new regime, since the whole comparison only applies under the old one.
Once the right mix is picked on paper, the last piece is turning it into an actual filing strategy.
Every planning beats last-minute scrambling every year.
Start investing early in the financial year rather than rushing in March.
Use the full ₹.1.5 lakh limit rather than leaving part of it unclaimed.
Spread contributions across instruments that balance safety and growth, PPF for stability, ELSS for growth, NSC for a conservative fixed-income anchor.
Claim the additional ₹50,000 under Section 80CCD(1B) through NPS once the ₹1.5 lakh limit is filled.
Keep every investment in the taxpayer’s own name, with documentation ready well before ITR filing.
Takeaway:
80C works best paired with Section 80D rather than used in isolation. Health insurance premiums add ₹25,000 for self, spouse, and dependent children (₹50,000 if a covered person is a senior citizen), plus a separate ₹25,000 or ₹50,000 for parents depending on age.
This is also where the operational side of tax planning tends to show up. Collecting several hundred investment declarations by hand every January, matching each one against the right taxpayer type and document, and reconciling it all before Form 16 generation is rarely a light lift for a payroll team.
A platform like Keka that centralizes declarations, proof uploads, and validation ahead of Form 16 generation turns that into a far less manual process, and that matters more the larger the workforce gets.
Section 80C rewards planning over improvisation. Filling the ₹1.5 lakh deduction limit early, making the most of the additional ₹50,000 under Section 80CCD(1B) where applicable, and keeping investment proofs ready well before the filing deadline can help employees maximise tax savings while avoiding last-minute stress.
For HR and payroll teams, the challenge isn’t understanding Section 80C. It’s managing hundreds of investment declarations, validating supporting documents, updating payroll records, and ensuring Form 16 reflects the right deductions before tax season begins. As organisations grow, that process quickly becomes difficult to manage through spreadsheets and email trails alone.
Keka helps simplify that process by bringing investment declarations, proof collection, payroll records, and Form 16 generation into a single workflow. With complete visibility into employee declarations and supporting documents, HR teams can stay compliant, reduce manual effort, and approach tax season with confidence.
Tax Savings Start with Smarter Payroll
Q1. What is 80C deduction?
Section 80C is a provision under the Income Tax Act that lets individuals and HUFs claim a deduction of up to ₹1.5 lakh from taxable income through specified investments or eligible payments, including PPF, ELSS, life insurance premiums, NSC, EPF, Sukanya Samriddhi Yojana, home loan principal repayment, and tuition fees.
Q2. What is the maximum deduction limit under Section 80C for FY 2025-26?
₹1,50,000 per financial year, shared across Sections 80C, 80CCC, and 80CCD(1) under Section 80CCE. An additional ₹50,000 is available separately under 80CCD(1B) for NPS.
Q3. Is Section 80C available under the new tax regime?
No. Only the old tax regime allows 80C claims. Whether it’s worth switching depends on whether total deductions, 80C plus 80D plus HRA plus others, outweigh the lower slab rates the new regime offers.
Q4. Who can claim deduction under Section 80C?
Only individuals and HUFs can claim Section 80C deductions. Companies, firms, and LLPs are not eligible for this deduction.
Q5. Can HUF claim 80C deduction?
Yes, up to ₹1.5 lakh, provided the investment comes from HUF funds. Life insurance premiums for HUF members, PPF contributions, and ELSS investments made through the HUF account all qualify.
Q6. Can HUF claim 80C deduction for LIC?
Yes, for premiums paid on policies covering HUF members such as the karta or coparceners, as long as the payment comes from the HUF account.
Q7. Does PF deduction come under 80C?
The employee’s own EPF contribution qualifies. The employer’s matching contribution does not, since it’s treated as a separate exempt benefit.
Q8. What is the lock-in period for ELSS investments under Section 80C?
Three years, the shortest among common 80C options. Tax-saving FDs and NSC run 5 years, PPF runs 15, and SSY matures at 21 years from account opening.
Q9. Can I claim both 80C and 80D?
Yes. Section 80D runs alongside 80C, offering ₹25,000 for self, spouse, and dependent children (₹50,000 if a senior citizen is covered), plus a separate ₹25,000 or ₹50,000 for parents depending on age.
Subscribe to keep up with the latest strategic finance content.
Request a demo