


 Login


Form 8822-B
Read Time: 5 Mins


PRODUCTS
 Payroll Suite
 HR Suite
 Talent Suite
 Project Services Suite

Meet the platform tailored to your business
Core system of record
One platform for the entire employee journey

BY INDUSTRY
BY COMPANY SIZE
LEARN
EXPLORE KEKA
Form 8822-B is an IRS form businesses use to update the information originally provided when applying for an EIN (Federal Tax ID Number). It notifies the IRS of changes to the business mailing address, principal place of business, or the responsible party.
In other words, Form 8822-B serves as the IRS’s method for staying informed about changes in a business’s details.
Whether a business has relocated to a new address, updated its mailing location, or changed its responsible party for tax matters, this form ensures the IRS receives the necessary updates. Filing it within 60 days of any changes is essential to avoid potential penalties or miscommunications with the agency.
Form 8822-B is vital in keeping the IRS informed about critical business updates. Submitting this form ensures businesses stay compliant and continue receiving vital tax communications without interruption, whether due to a change in mailing address, relocation of the principal place of business, or the appointment of a new responsible party.
The form must be filed within 60 days of these changes.
Accurate reporting of the responsible party—defined as the individual or entity with control over the business’s assets or funds—is critical to avoid compliance issues.
Any business with an EIN (Employer Identification Number) is required to file Form 8822-B when such updates occur. This includes domestic and international companies, nonprofits, and other entities using an EIN for tax purposes. If there’s a change in the responsible party, their updated name and identification details must be included in the submission.
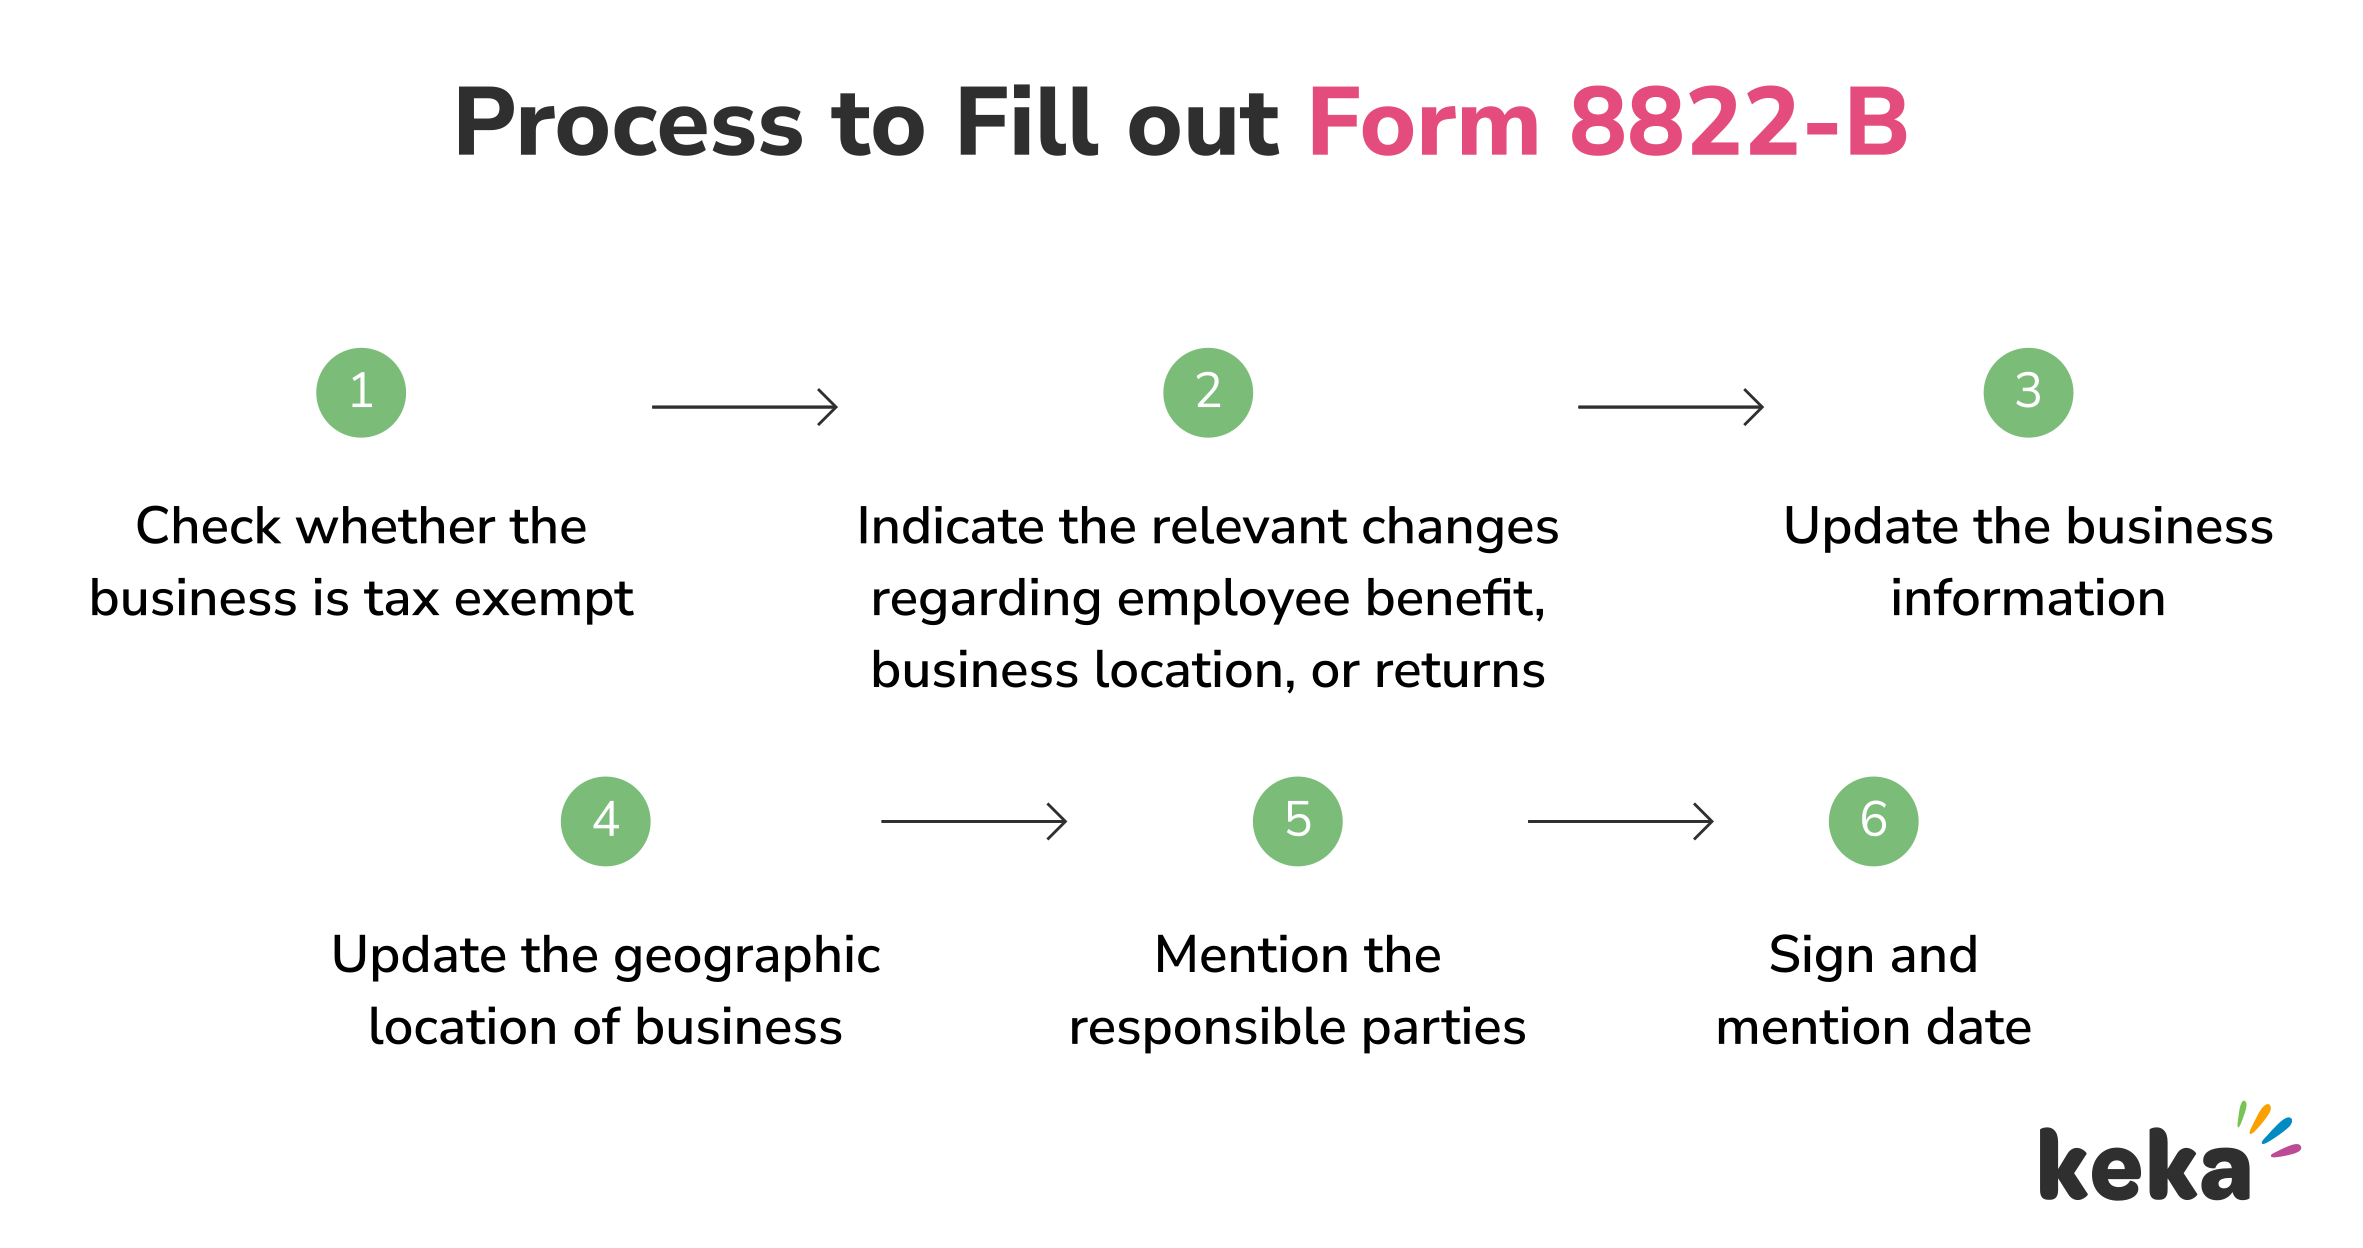
1. Tax-Exempt Status: If the business holds tax-exempt status, the appropriate box at the top of the form must be checked to ensure proper processing.
2. Indicate Relevant Changes:
3. Business Information: Line 4 should include the business name and EIN as registered with the IRS.
4. Address Updates:
5. Responsible Party Update: Lines 8 and 9 should reflect the name and SSN, ITIN, or EIN of the new responsible party responsible for managing the business’s assets or tax-related matters.
6. Sign and Date: The form must be signed and dated by an authorized officer or business owner, with their title clearly noted.
Form 8822-B must be submitted by mail, and the mailing address depends on the location of the business’s previous address:
The IRS mailing address for submitting Form 8822-B depends on the location of the business’s old address:
In terms of timing, Form 8822-B must be submitted within 60 days of a change in the responsible party, mailing address, or physical location. While address changes can be filed anytime, it’s advisable to act promptly to ensure IRS records remain current. Processing typically takes 4–6 weeks, so filing early helps avoid potential delays.
Failing to file Form 8822-B won’t incur penalties, but it can lead to serious complications. Without updated information, businesses risk missing critical tax notices, such as deficiency or payment demands, which could cause delays in addressing tax matters.
Interest and penalties on unpaid taxes will continue to accrue, even if communication issues arise.
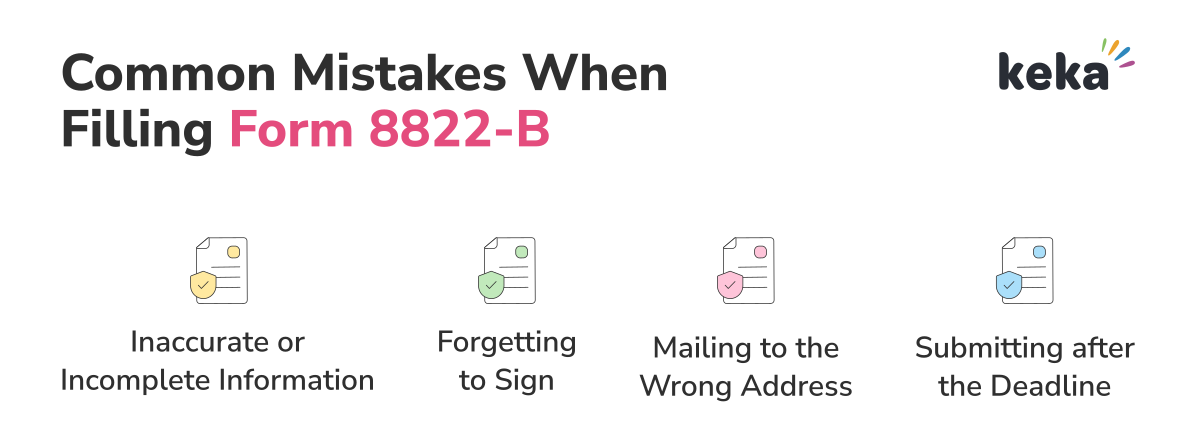
Ensure all fields are correctly filled out, including the business name, EIN, previous and updated addresses, and responsible party details. Double-check for accuracy before submitting.
The form must be signed by an authorized business owner or representative. If a representative is signing, they must include Form 2848 (Power of Attorney and Declaration of Representative) to validate their authority.
Refer to the IRS-provided table to identify the correct mailing address. If the address change involves different states, use the address corresponding to the old location.
The form must be filed within 60 days of an address or responsible party change. Delayed submissions can lead to penalties or missed communications from the IRS.
Subscribe to keep up with the latest strategic finance content.
Request a demo


