Login


Form 5498
Read Time: 9 Mins


PRODUCTS
 Payroll Suite
 HR Suite
 Talent Suite
 Project Services Suite
Meet the platform tailored to your business
Core system of record
One platform for the entire employee journey
How Srijan Technologies streamlined timesheets management with Keka
Read customer story
BY INDUSTRY
BY COMPANY SIZE
LEARN
EXPLORE KEKA
Navigate every labor law, wage regulation, and statutory requirement across all 28 states and 8 union territories without the legal headaches.
Learn More
Form 5498 is an Internal Revenue Service (IRS) tax form that outlines contributions and other details about your Individual Retirement Accounts (IRAs). The institution that administers your IRA will send you Form 5498. You will receive Form 5498 because it documents contributions, rollovers, Roth IRA conversions, and Required Minimum Distributions.
Form 5498 is sometimes referred to as a ‘5498-tax statement’, which is the same as a 5499-tax statement. The IRA custodian or trustee is required to send you the IRS Form 5498 on or before May 31 of each year.
Financial institutions issue Form 5498 to report contributions and related information for various tax-advantaged retirement accounts. Below are the account types and what the form typically reports for each.
Form 5498 reports annual contributions, rollover amounts, recharacterizations, and the fair market value (FMV) of the account for Traditional IRAs. If the account holder is required to take required minimum distributions (RMDs), the form also includes relevant RMD information.
For Roth IRAs, the form reports contributions and any conversions from Traditional IRAs or other eligible retirement plans. While Roth IRAs do not have RMD requirements during the owner’s lifetime, Form 5498 still includes FMV and contribution details.
SEP IRA contributions, which employers typically make on behalf of employees, are reported on Form 5498. The form includes the total contribution amount and the FMV of the account.
Form 5498 is also used to report both employer and employee contributions made to SIMPLE IRAs. Like other IRAs, the FMV of the account is also reported.
In the case of inherited IRAs, Form 5498 reports the fair market value and distribution-related information. If the account holder is required to take distributions, Box 11 of the form may be checked to indicate this obligation.
When a rollover occurs from one retirement account to another. For example, from a 401(k) to a Traditional IRA, the amount is reported on Form 5498 as a rollover contribution.
If an individual recharacterizes a contribution from one type of IRA to another such as moving a Roth IRA contribution back to a Traditional IRS, the recharacterization is reported on Form 5498.
If funds are transferred from an IRA to a Health Savings Account (HSA) under the Qualified HSA Funding Distribution provision, Form 5498 reports this transaction as well.
Form 5498 has all the details about your IRA. Here’s a breakdown:
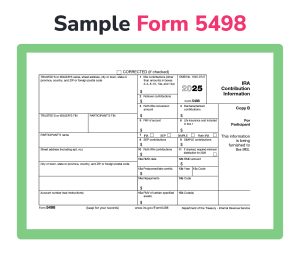
Other boxes cover late rollover contributions, disaster-related repayments, and FMV for unique asset types.
For all 2024 IRAs, Form 5498 must be filed with the IRS by May 31, 2025, and a copy must be sent to the account holder by the same date.
If the filing deadline falls on a weekend or holiday, the deadline is the next business day.
Here’s a step-by-step guide for filling out Form 5498:
Step 1: List accounts requiring Form 5498
File Form 5498 for each IRA, Traditional, Roth, SEP, and SIMPLE IRAs. If multiple accounts are under one IRA, only one form is required. A separate form is required for the same custodian.
Step 2: Gather information for the accounts
Step 3: Fill out Form 5498. Ensure checking the above-mentioned Box 1-7.
Step 4: Review the form thoroughly and submit it.
Custodians and trustees handling Traditional, Roth, SEP, and SIMPLE IRAs must comply with strict IRS reporting deadlines. Below are the key dates:
| Form/Statement | Purpose | To the IRS by | To IRA Owner by |
| IRS Form 1099-R | Reports distributions | February 28 (paper) / March 31 (electronic) | January 31 |
| FMV Report | Reports Fair Market Value (FMV) | May 31* (June 2, 2025) | January 31 |
| RMD Notice | Reports RMD-related information | May 31* (June 2, 2025) | January 31 |
| IRS Form 5498 | Reports contributions and FMV | May 31* (June 2, 2025) | May 31* (June 2, 2025) |
*If a deadline falls on a weekend or holiday, it is extended to the next business day.
SIMPLE IRAs follow similar reporting rules but have extra deadlines specific to plan adoption and annual notices.
| Form/Statement | Purpose | To the IRS by | To IRA Owner by |
| Statement of Account Activity | Reports account activity | N/A | January 31 |
| SIMPLE Adoption | Deadline to adopt a SIMPLE plan | N/A | *October 1 (before 60-day election period) |
| SIMPLE IRA Employer Notice | Annual notice to eligible employees | N/A | November 1 (before 60-day election period) |
| Summary Description | Provides required information to employees | N/A | November 1 (before 60-day election period) |
*The deadline to adopt a SIMPLE plan for the current year is October 1, 2025, for 2025 plans.
Health Savings Accounts (HSAs) have distinct reporting timelines for contributions and distributions.
| Form/Statement | Purpose | To the IRS by | To HSA Owner by |
| IRS Form 1099-SA | Reports distributions and date-of-death FMV | February 28 (paper) / March 31 (electronic) | January 31 |
| IRS Form 5498-SA | Reports contributions and FMV | May 31* (June 2, 2025) | January 31 |
Coverdell Education Savings Accounts (CESAs) have specific deadlines for reporting contributions and distributions.
| Form/Statement | Purpose | To the IRS by | To Participant by |
| IRS Form 1099-Q | Reports distributions, including transfers | February 28 (paper) / March 31 (electronic) | January 31 |
| IRS Form 5498-ESA | Reports contributions and transfers | May 31* (June 2, 2025) | April 30 |
*Deadlines are extended to the next business day if they fall on a weekend or legal holiday.
If you notice an error on Form 5498, it’s important to address it promptly, as the information is reported directly to the IRS and may affect your tax records. Here’s what you should do:
Start by verifying the details reported on the form, including:
Even small discrepancies like an incorrect contribution year should not be ignored.
If you find an error, reach out directly to the bank, brokerage firm, or trustee that issued the form. Most institutions have a process for reviewing and correcting reporting mistakes. Be prepared to provide documentation (like account statements or transaction confirmations) to support your claim.
If the institution agrees that an error was made, they should issue a Corrected Form 5498. This corrected form will replace the inaccurate one and be re-submitted to the IRS to amend their records as well.
Form 5498 is for informational purposes only and does not need to be submitted with your personal tax return. However, any errors, especially those affecting contribution limits or rollover status can trigger IRS follow-up if left uncorrected.
Keep a copy of the original and corrected Form 5498 along with your correspondence and any documentation submitted. This will be helpful in case of future IRS inquiries.
If the institution fails to correct the issue or you disagree with their response, you may need to escalate the matter. This could include filing a complaint with the IRS or consulting a tax professional for further steps.
Form 5498 is an informational document. While you don’t have to attach it to your tax return, it ensures your reported IRA contributions and rollovers match your tax filings.
Please note that: You don’t need Form 5498 to file your taxes, but keep it for your records to verify contributions and rollovers.
No, Form 5498 and Form 1099-R are different. Here’s how:
Form 1099-R shows both taxable and non-taxable amounts so you can figure out what part of your distribution needs to be reported as income.
Form 5498 shows IRA contributions, rollovers, conversions, and the Fair Market Value (FMV) of the account at year-end.
If you took distributions or rolled over funds into an IRA in the same year you may get both forms, but they show different things about your retirement account activity.
Here’s a comparison table highlighting the key differences between Form 5498 and Form 1099-R:
| Feature | Form 5498 | Form 1099-R |
| Purpose | Reports IRA contributions and account information | Reports distributions from retirement accounts |
| Who Files It | Financial institution (trustee or custodian) | Financial institution (trustee or custodian) |
| Who Receives It | IRS and the IRA account holder | IRS and the taxpayer receiving the distribution |
| Filed When | When contributions are made (including prior-year contributions made by April) | When money is taken out of a retirement account |
| Commonly Includes | Contributions (Traditional, Roth, SEP, SIMPLE), rollovers, FMV, RMD info | Distributions, early withdrawal penalties, taxable amounts |
| Tax Filing Impact | Informational only; not filed with your tax return | Used to report income; must be included in tax return |
| Due to IRS By | May 31 | January 31 |
| Typical Box Items | Contribution amounts, rollover, FMV, RMD checkbox | Gross distribution, taxable amount, federal tax withheld |
Subscribe to keep up with the latest strategic finance content.
Request a demo